The money · the firm, argued from the outlook's claims
A firm rents what it can check and owns what it must answer for.
A firm is a line drawn round some work. Inside it, people are told what to do; outside it, things are bought. Economists have long explained where the line falls by what it costs to deal with strangers. AI models are now sold by the token, a fragment of a word, so a firm can buy thinking by the unit as it buys electricity. This essay asks where the line moves when that is so, and sets out what this site's records show. The title is this site's own reading, argued in the third folio; no one writer cited here makes it whole.
●holding so far3×failing its test0◑both sides expect this2○can't be tested yet22
Folio I · the boundary
A firm ends where buying gets cheaper than managing
Ronald Coase, a British economist, asked in 1937 why firms exist if prices can settle who makes what. His answer was that using a market is not free. Someone has to find out prices, bargain, and write a contract for every exchange: the transaction costs. Inside a firm a manager's instruction replaces all of that. A firm, "that little planned society" as he later called it, grows until organising one more job inside costs as much as buying it outside 1.
An AI agent, a model set to carry out tasks on someone's behalf, can search, compare and bargain for almost nothing. Peyman Shahidi, John Horton and their colleagues, who study online markets, called the prospect a Coasean singularity, the point at which dealing costs almost nothing, with a question mark, and expect the line between making and buying to move 2. One of them works for Amazon and another is a paid adviser to Anthropic. They do not say firms vanish, and they list new frictions agents bring.
Coase's rule has two sides, and cheap intelligence lowers both. Gillian Hadfield, who designs legal and regulatory systems for AI, and Andrew Koh, who studies how to design markets, observe that what stops a firm growing without limit is a set of obstacles that "seem intrinsic to humans but not to AI" 3. So the rule cannot say by itself whether firms shrink or grow. Something else decides, and the next three folios take the candidates in turn: what a firm knows, what it must answer for, and where its decisions have to be taken.
The positions on this question, and tonight's reading of each claim
Cheap agents move the firm's boundary; they do not remove it
Shahidi, Horton and colleagues; Gillian Hadfield and Andrew Koh; Soren Larson
Agents cut the cost of finding, bargaining and contracting, and they cut the cost of managing as well, so both sides of Coase's comparison fall 1. The authors who named the Coasean singularity put a question mark on it themselves and list the new frictions agents bring 2.
○can't be tested yetFirms in the industries most exposed to AI do not shrink towards nothing as agents cut the cost of dealing.
None of the writers this page read argues that firms vanish, and 24.6% of American firms say they use AI at all, so any change in the size of firms lies ahead of the readings.
What would refute it
Firms in the industries most exposed to AI shrinking sharply as work moves to independent contractors and their agents.
No reading tests this yet. Proved wrong by: Average firm size in the most exposed industries falling sharply while it holds elsewhere. This site reads firm size by industry for one year only, so nothing tests it yet.
With dealing nearly free, most work is bought in and firms shrink towards nothing
This site's own position
If a firm exists only because dealing with outsiders is costly, then agents that deal for almost nothing leave little reason to employ anyone. This is the popular reading of the Coasean singularity; no writer this page read holds it as stated.
Soren Larson, who writes about how money moves between AI labs, the companies that train the largest models, and the apps built on them, turns Coase round. If every firm rents the same models, what separates one firm from another, once trust and customers' attention are set aside, is context: what it knows about its customers, its costs and its plans. To buy from a market a firm has to say what it wants, and saying so reveals context. Even a request for bids tells rivals what the firm thinks matters. On his account the firm exists "to prevent the extraction of its scarce context" 4. The cost of dealing has not fallen. It has changed from the cost of finding a seller into the cost of being seen.
Two older results explain why no market repairs this. Kenneth Arrow, an economist who studied how markets handle knowledge, showed that a buyer cannot tell what information is worth until he has it, and then need not pay 5. George Akerlof, who studied markets in which sellers know more than buyers, showed that when quality cannot be seen, good goods are withdrawn and the market shrinks 6. A firm cannot sell its context without giving it away, or buy another's without guessing at its quality. So it keeps what it knows and acts on it itself.
The two sides predict different things. Shahidi and his colleagues expect agents to search and bargain across markets for whoever deploys them; Larson expects them to stay inside the firm or be kept off other firms' platforms. This site holds no record that tests it. A count of firms buying knowledge-heavy work through independent agents would settle it, and nobody publishes one.
The positions on this question, and tonight's reading of each claim
Asking reveals what you want, so firms keep work inside
Soren Larson
When everyone has the same models, what a firm knows about its own needs is its edge, and asking the market for help gives it away.
○can't be tested yetFirms keep inside the work that would reveal what they know, and independent agents dealing for firms in open markets stay rare.
No reading tests this yet. Proved wrong by: Independent agents dealing on firms' behalf at scale in open markets, for work that turns on the firm's own knowledge. Nobody publishes a count of it.
Agents arrive first where wants are simple and agents already work
Shahidi, Horton and colleagues
Handing a task to an agent is easiest where people already hire agents and can say simply what they want.
○can't be tested yetAgents take hold first in job search, property and other matching markets.
No reading tests this yet. Proved wrong by: Agents spreading first in markets where people rarely hire human agents.
Folio III · the liability
Whoever must answer for the work ends up owning it
Sanford Grossman and Oliver Hart, economists who studied contracts, asked in 1986 what ownership is for. No contract can list everything that might happen. Where it is silent someone has to decide, and they defined owning an asset as holding that right: "Ownership is the purchase of these residual rights" 7. Ownership has a price, since control given to one party is taken from another, so it should rest with the party whose decisions matter most.
Hadfield and Koh point out that instructing an AI is a contract of this kind: what a designer tells a model to aim at can never cover every case 3. They ask who answers when it goes wrong, and find the law unready, since few legal systems hold anyone liable for acts they could neither foresee nor control.
This site joins the two, and the join is its own reading, not theirs. If an agent's instructions are incomplete, someone must decide in the gaps and bear the loss, and Grossman and Hart's result says that someone should own the operation. Byrne Hobart, who writes The Diff, a newsletter on finance and technology, arrives there from the buyer's side. Once software acts for long stretches with some randomness, the buyer asks whom to sue. A small seller of agents has the least to lose, so the work is bought from a firm with assets, customers and a name to lose, and a seller sure of its software may do best to own the business that uses it 8. He notes in passing that insurance written for agents is beginning to be sold. Christian Catalini, Xiang Hui and Jane Wu, economists who study the cost of verifying work, add that doing gets cheaper with computing power while checking is held up by people's time, so the profit moves to whoever can verify the work and stand behind it 9.
The rival view is that insurance and contract will carry the liability, so nobody need own anything. Over the past year this site has recorded 4 moves by insurers to write AI's mistakes out of their standard policies. One of those moves was an insurer selling separate cover for AI as it took it out of the standard policy. Both sides expect exclusions first. They part on what comes next: cover for AI sold widely, which would favour the rival, or operators absorbing the risk. Nobody publishes the premiums written for such cover, so tonight's reading cannot tell them apart.
The positions on this question, and tonight's reading of each claim
Whoever must answer for the work ends up owning the operation
An argument of Grossman and Hart; Gillian Hadfield and Andrew Koh; Byrne Hobart; Soren Larson, carried further by this site
An instruction to an agent cannot cover every case 3, so someone must decide in the cases it missed and pay when the work is wrong. Where a contract cannot be completed, ownership settles who decides 7; so the party that bears the loss wants to own the operation, and a seller with nothing to lose is a poor party to buy from 8. None of these writers makes the whole argument; this site joins them.
◑both sides expect thisInsurers go on writing AI's mistakes out of their standard policies, so whoever deploys an agent carries the loss unless it buys separate cover.
●holding so farBuyers built around AI go on purchasing firms that sell services, more each year than the year before.
○can't be tested yetService firms bought by owners built around AI earn higher margins afterwards than rivals that only buy the same tools, in trades not billed by the hour.
Buyers built around AI bought 41 firms that sell services in the past year, against 24 the year before, and insurers have moved 4 times in a year to write AI's mistakes out of their standard policies. Neither reading shows that owning pays.
What would refute it
Sellers that own no operation and hold no licence carrying the liability for consequential AI work by contract and insurance, at scale.
Insurers go on writing AI's mistakes out of their standard policies, so whoever deploys an agent carries the loss unless it buys separate cover.
Tonight 4; the test is at least 1. Its rival can live with the same reading, so tonight settles nothing. Proved wrong by: Standard liability policies covering AI's mistakes at no extra price. The rival view also expects exclusions first, so what would separate the sides is the premiums written for AI cover, which nobody publishes.
Buyers built around AI go on purchasing firms that sell services, more each year than the year before.
Tonight 41; the test is above 24. Proved wrong by: The yearly count of such purchases by the same searched buyers flat or falling. The count is a floor from one search of the larger buyers, and it shows what buyers did, not that owning paid.
Service firms bought by owners built around AI earn higher margins afterwards than rivals that only buy the same tools, in trades not billed by the hour.
No reading tests this yet. Proved wrong by: Such firms' margins falling back to their trades' ordinary level within a few years of purchase. This site holds no margin for any of them.
Insurance and contract carry the liability, so nobody needs to own the operation
This site's own position
If insurers learn to price an agent's mistakes, a software seller can buy cover and warrant its work, as contractors do, and the buyer need not care who owns what.
The forecasts board on this site, a model's judgement, leans this way; it expects insurers to sell cover written for AI and doubts that AI's work will mostly be bought through firms that can be sued.
What would refute it
Insurers going on writing AI out of standard cover while cover written for it stays small.
AI's work is bought through firms that can be sued
Byrne Hobart
When an agent does long, unpredictable work, the buyer wants someone with assets and a licence who answers for its mistakes, so AI reaches customers through such parties.
○can't be tested yetFirms increasingly buy AI's work through a party with assets and a licence that can be held liable, such as an established service firm.
Hobart expects labs to buy operating firms in the trades they serve, gaining customers and assets that can answer for mistakes.
What would refute it
Buyers taking AI's work on long, unpredictable tasks from parties that cannot answer for its mistakes.
No reading tests this yet. Proved wrong by: Buyers taking AI's work on long, unpredictable tasks from parties that cannot answer for its mistakes.
Folio IV · the edge
Knowledge can be sent to the centre; acting on it sometimes cannot
Friedrich Hayek, an economist who studied how prices carry what people know, argued in 1945 that much of the knowledge an economy runs on is "the knowledge of the particular circumstances of time and place" 10, which no central office can collect, so decisions belong with the person on the spot.
Erik Brynjolfsson, who directs Stanford's Digital Economy Lab, and Zoë Hitzig, who studies AI's effects on society, argue that AI undoes much of this. Hitzig worked at OpenAI when they wrote and has since joined a research institute run by Anthropic. It records what used to go unwritten and lets a head office process far more, so they predict "larger average firm size, greater industry concentration, and reduced local managerial autonomy" 11. This site sets beside them a finding they do not cite. Rich Sutton, a computer scientist who studies how machines learn, found that over decades of AI research, methods built on what experts know were beaten by general methods that improve as computing gets cheaper 12. He was writing about research, not firms; the reading across is this site's.
Chris Walker, who writes on the economics of unwritten knowledge, replies that writing knowledge down for a model is neither free nor complete. Choosing what a model needs to know for each task takes local judgement and has to be done again as the work changes. "The knowledge problem has not been solved", he writes; it has moved upstream 13. Larson grants that context can be gathered and still ends at the edge, the place where the work is done: running a model costs energy and time, and a car at speed cannot wait for an answer from a distant data centre 14.
The camps agree on more than their conclusions suggest. Both draw a line between what can be recorded and what cannot, and both leave time-critical decisions at the edge: Brynjolfsson and Hitzig themselves list decisions that must be taken faster than a message can travel, beside rare cases, bodily skill and whatever the law reserves for people. They differ on whether the line moves. Brynjolfsson and Hitzig think the exceptions may shrink as models improve; Walker expects each new ability to open new work that needs local judgement. Delay is the floor neither side disputes, and energy is Larson's addition. Brynjolfsson and Hitzig name the test, whether firms that adopt AI move decisions to the centre; Walker's own dated predictions turn on firm size, and no one holds a series that reads either.
The positions on this question, and tonight's reading of each claim
Decisions move to the centre
Erik Brynjolfsson and Zoë Hitzig
AI captures the local knowledge that used to justify leaving decisions to people on the spot.
○can't be tested yetFirms using AI grow larger and take decisions further from the people on the spot.
No reading tests this yet. Proved wrong by: Firms getting smaller and more decentralised as they adopt AI.
Big at the base, small at the top
Chris Walker
Codifying a firm's knowledge for AI is costly, lossy and needs upkeep, so scale pays where the work is generic, in computing and models, while firms closest to a trade's own knowledge win in applications.
○can't be tested yetFirms in AI-exposed industries do not all grow bigger by 2029; they consolidate in infrastructure and splinter in applications.
○can't be tested yetFirms that adopt AI move routine, recordable decisions to the centre and leave fast-changing and time-critical ones with local units; they do not centralise across the board.
Firms in AI-exposed industries do not all grow bigger by 2029; they consolidate in infrastructure and splinter in applications.
No reading tests this yet. Proved wrong by: Average firm size rising in AI-exposed industries, applications included, by 2029.
Firms that adopt AI move routine, recordable decisions to the centre and leave fast-changing and time-critical ones with local units; they do not centralise across the board.
No reading tests this yet. Proved wrong by: Adopting firms centralising decisions of every kind, the fast-changing included, and doing better than those that leave them local. No series on this site records where decisions are taken.
Knowledge on the spot keeps decisions there
An argument of Friedrich Hayek, carried further by this site
What matters for most decisions is knowledge of particular times and places, which changes constantly and by its nature cannot reach the centre as statistics. Hayek argued it about central planning; this site carries it to AI.
○can't be tested yetLaw, contracting and other trades scattered by place stay split among many small firms, while the AI tools each trade uses gather around a few vendors.Claimed by Byrne Hobart
The knowledge Hayek meant is local and fleeting and cannot be gathered into statistics; this site adds that a model trained on what is written may lack it.
What would refute it
Firms that move decisions to the centre with AI outperforming those that leave them local.
No reading tests this yet. Proved wrong by: A handful of labs ending up running, and profiting from, most professional work directly.
AI's everyday work moves onto people's own devices
Chris Paik
Once a small model on a phone or laptop is good enough, running it there is cheaper and faster than paying a data centre for each request, and the meter stops.
○can't be tested yetMuch of AI's everyday work moves out of distant data centres onto people's own phones and laptops.
○can't be tested yetWork that must be decided faster than a message can reach a data centre, or on little power, is run on the spot, whoever holds the knowledge.Claimed by Soren Larson
Open models a few steps behind the best keep getting better, and each release widens what a device can do on its own.
What would refute it
Everyday use staying in cloud data centres even as capable open models shrink.
Much of AI's everyday work moves out of distant data centres onto people's own phones and laptops.
No reading tests this yet. Proved wrong by: Everyday use staying in cloud data centres as capable open models get smaller.
Work that must be decided faster than a message can reach a data centre, or on little power, is run on the spot, whoever holds the knowledge.
No reading tests this yet. Proved wrong by: Time-critical work such as driving and industrial control moving to distant data centres as networks improve.
Folio V · the rent
Most firms should rent intelligence; a few should own it
There are two reasons to rent. The lead is short: open models, whose trained settings are published for anyone to run, trail the best closed ones by 7.7 months, so a firm that trains its own is buying something that loses value fast. And most firms see nothing in their own work that others do not see: in a simulation of his own, Larson found that a system trained on other firms' results did better than one trained on a firm's own history 15. Luis Garicano, an economist who studies how firms organise what they know, and Jesús Saa-Requejo put it plainly: "Intelligence is not what stops most organisations from doing what they want to do" 16.
The risk in renting is set out by Garicano and Saa-Requejo too. A supplier of rented intelligence can raise its price once a firm's work depends on it, and can learn the firm's business by watching how it is used 17. That is Larson's leak again, with the lab as the party watching. Their remedy is not to own the model. It is to rent it, to own the rules and records that sit above it, and to keep a second supplier within reach. So the answer turns on what is scarce in the firm's own work.
When to rent intelligence, and when to own itA model, not a measurement
What is scarce in the firm's workRentOwnWho wins
Nothing the firm alone can see, and a cheap check exists
Rent by the token, from more than one seller. The firm's customers, once rivals rent the same; and whoever pools many firms' results
A signal only this firm senses
Own the sensors and the model trained on what they read. The owner-operator, for as long as the signal stays its own
Time or power at the point of work
Own small models and run them on the spot. Whoever owns the device or the site
The right to sign, and the loss when the work is wrong
Rent the model, own the licensed operation. The licensed firm, and whoever insures it
Secrecy, where being seen is the loss
Keep the model inside, on machines the firm controls. The firm, and sellers of private installations
The frontier itself
Own. The labs, for as long as their lead lasts
Use so heavy and steady that paying by the token costs more than running machines
Run an open model on owned or leased chips. The firm, and the owners of chips and power
This site's reading of the writers cited on this page. It is a judgement, and no row has a test of its own; the last row rests on no source and is the weakest.
Most firms sit in the first row. The rows are the cases in which this site judges owning wins; they are fewer firms than the first row holds.
The cases as a table, with examples
What is scarce in the firm's work
An example
Rent or own
Who wins
Nothing the firm alone can see, and a cheap check exists
Answering routine customer queries; keeping the books
Rent by the token, from more than one seller
The firm's customers, once rivals rent the same; and whoever pools many firms' results
A signal only this firm senses
A fleet of driverless cars; a ring that reads its wearer's body (both among Soren Larson's examples)
Own the sensors and the model trained on what they read
The owner-operator, for as long as the signal stays its own
Time or power at the point of work
A vehicle at speed; a camera running on a battery
Own small models and run them on the spot
Whoever owns the device or the site
The right to sign, and the loss when the work is wrong
An audit opinion; a prescription; an insurance policy
Rent the model, own the licensed operation
The licensed firm, and whoever insures it
Secrecy, where being seen is the loss
A trading strategy; a product not yet announced
Keep the model inside, on machines the firm controls
The firm, and sellers of private installations
The frontier itself
Training the most capable model
Own
The labs, for as long as their lead lasts
Use so heavy and steady that paying by the token costs more than running machines
A service that calls a model at every step for every user
Run an open model on owned or leased chips
The firm, and the owners of chips and power
Clayton Christensen, who studied why leading firms lose their lead, gave the general rule: when one part of a product becomes good enough and interchangeable, the profit moves to the neighbouring part that still limits performance 18. Intelligence by the token is becoming that part. Larson cautions against his own case: owning every step does not make a firm safe, because AI also makes it cheap to stitch separate pieces into something good enough 19.
The positions on this question, and tonight's reading of each claim
Most firms should rent intelligence and own something else
Soren Larson; Garicano and Saa-Requejo
The best model's lead over open ones is short, so a firm that owns its intelligence owns a wasting asset; and most firms see nothing in their own work that others do not see, so a system that learns from many firms beats one that learns from one 15. What holds most organisations back is workflow, authority and data, not intelligence 16.
◑both sides expect thisUse of models stays spread across several labs and open models, with the concentration of routed tokens among labs below 0.25 index, and few firms train or run their own.
○can't be tested yetA model of a firm's own pays only where the firm senses something no one else can; elsewhere a system trained on many firms' results does better.Claimed by Soren Larson
Use of models stays spread across several labs and open models, with the concentration of routed tokens among labs below 0.25 index, and few firms train or run their own.
Tonight 0.24 index; the test is below 0.25 index. Its rival can live with the same reading, so tonight settles nothing. Proved wrong by: Use concentrating on one lab's models while open ones fall further behind, or a current survey finding most large firms running their own. The reading is developers' routed tokens, not firms' spending, and the rival speaks of who runs a model, not whose it is, so it accepts the same reading. A router's traffic is all rented, so this reading can show spread among sellers and cannot show renting against owning.
A model of a firm's own pays only where the firm senses something no one else can; elsewhere a system trained on many firms' results does better.
No reading tests this yet. Proved wrong by: Systems tuned on a firm's own history beating pooled ones in trades where no firm senses anything scarce. The only evidence so far is its author's own simulation.
A firm that rents its thinking teaches its supplier its business
An argument of Garicano and Saa-Requejo, carried further by this site
A supplier of rented intelligence sees how its customer works, can raise its price once the customer's work depends on it, and can learn enough to compete 17. Garicano and Saa-Requejo answer by renting the model while owning the rules and records above it and keeping a second supplier. This site carries their warning further, to the case for owning the model itself.
Some things do not get cheaper when intelligence does
Philippe Aghion, Benjamin Jones and Charles Jones, economists who study growth, argued that when tasks depend on one another, growth may be held back by "what is essential and yet hard to improve" 20. Value collects at whatever stays slow, and inside a firm several things do.
Attention: a customer has the same hours in the day whatever a model costs. Ben Thompson, who writes on technology strategy at Stratechery, showed how firms that own the relationship with users make their suppliers interchangeable 21. Accountability: a model cannot be sued, fined or struck off, and a firm can. Trust: one of the answers Akerlof named for quality nobody can see was a name with something to lose. Permission: licences, regulators and courts decide who may act, and Brynjolfsson and Hitzig count them among the limits on their own prediction. And unwritten judgement: knowing what good work looks like in a trade.
The last is the one most likely to give way. If models come to learn on the job, what is unwritten today is recorded tomorrow, and Walker says he is wrong if general agents manage complex work inside firms without continuing human help by 2028.
The positions on this question, and tonight's reading of each claim
What goes first is set by the cost of checking, not the cost of doing
An argument of Gillian Hadfield and Andrew Koh, carried further by this site
A task is handed over when checking the result costs less than doing it. Hadfield and Koh argue about accountability; this site carries the argument to the order of adoption.
○can't be tested yetMore knowledge work is held back by the lack of a check than by what the work requires, so what a firm keeps is the checking and the answering.This site's reading, not the author's
Code that comes with tests is handed to AI before contracts that come with none.
What would refute it
Work that is hard to check being handed over as fast as work that is easy to check.
No reading tests this yet. Proved wrong by: A later run of this site's census, under the same rule, finding more payroll passing its screen than waiting on a check without new checks having been built; or models checking their own work as reliably as an outside check does. The census is a screen scored by AI models, not a record of observations, so no nightly test reads it.
Folio VII · the shape
The pyramid thins where work can be checked, and keeps whoever must answer
A firm is drawn as a pyramid for a reason. Garicano argued in 2000, with a model, that a hierarchy is a way to economise on knowledge. The many at the base handle the common problems and pass the exceptions up to people who know more: "a knowledge-based hierarchy is a natural way to organize the acquisition of knowledge" 22. Nicholas Bloom, Garicano, Raffaella Sadun and John Van Reenen, who measure how firms are managed, later found that cheaper technology pulls two ways. Cheaper information gives people lower down more to decide; cheaper communication sends decisions back to the centre 23. They studied plants before AI, their paper does not say which of the two AI is, and this site has found no study that settles it.
Luke Drago and Rudolf Laine, who write on AI and the economy and now work at Thinking Machines, which builds AI, argue that AI empties the pyramid from the bottom. Firms first stop hiring at entry level, the jobs people start in, then lose their juniors, then their managers, until at a few there is nobody left 24. They give no dates and call the last step their most speculative. They mean large white-collar firms, and say policy or technology could change the course. Dario Amodei, who runs Anthropic, the company whose model drafted this page, has warned of the same first step: that "AI could displace half of all entry-level white collar jobs" within a few years 25. He says could, not will.
The evidence offered for that first step is a study of payroll records by Brynjolfsson, Bharat Chandar and Ruyu Chen: workers in their early twenties have fallen behind in the jobs most exposed to AI, mostly because fewer are hired, not because more leave or are let go 26. Zanna Iscenko and Fabien Curto Millet, economists at Google, which sells AI, objected to an earlier version that hiring in those jobs turned down before ChatGPT was released, as interest rates rose; they do not say entry-level work is safe later 27. The revised study says the gap remains after allowing for interest rates, and its authors call it an early sign, not proof of a cause.
Others expect the middle to go. Jack Dorsey, who runs the payments company Block, and Roelof Botha, a partner at the venture firm Sequoia, write of Block's own plans that a model of the whole company can carry what managers used to pass along: "There is no need for a permanent middle management layer" 28. They report no results and say parts of the plan will likely break. The one measurement this site has found is by Michael Ewens and Xavier Giroud, economists who estimated from online résumés how many layers of reporting listed American firms have. They report that "they flatten their hierarchies following the adoption of artificial intelligence" 29; their summary does not say which layers go, or that AI is the cause.
Garicano himself expects more managers, in a post written to say Amodei is wrong. A job is a bundle of tasks that is often costly to pull apart, and a firm is a coalition of people who want different things. Someone has to decide between them where no contract or rule does, be blamed for the result, and be seen as fair. AI could in principle come to hold that standing, he grants, but the law has built nothing to give it; until it does, "some human will have to hold the residual decision rights" 30, the right to decide whatever was not settled in advance. Julia Shin and Sandra Sucher, who write on management, found in a small set of interviews at two consulting firms that checking AI's work fell on the managers in the middle 31. At the far end, Shawn Bayern, a law professor, argued that American company law already allows an entity that follows a program and that no person owns or controls 32. Lynn LoPucki, another, accepts that and expects crime to use it first 33.
Shapes the firm might take, and who argues eachA model, not a measurement
The shape
Who argues it
What goes first
What stays
What would show it
A pyramid emptied from the bottom
Luke Drago and Rudolf Laine; Dario Amodei warns of its first step242526
Entry-level hiring, then junior roles
The executives longest; at a few firms nobody
Young workers' hiring falling in the jobs most exposed to AI while managers' numbers hold
A flatter firm, with the middle taken out
Jack Dorsey and Roelof Botha argue it; Michael Ewens and Xavier Giroud measure flatter firms and do not say which layer goes2829
Managers whose work is passing information along
People who do the work, and people answerable for a result
Fewer layers at firms that adopt AI than at similar firms that do not
The routine work by which juniors paid for their training
Seniors, each overseeing more; later, too few of them
Firms hiring fewer trainees and paying more for experienced staff
More managers, not fewer
Luis Garicano; Julia Shin and Sandra Sucher report the middle loaded with checking, not enlarged3031
Jobs made of a single task
Whoever holds the right to decide, and whoever checks the machine's work
The share of managers and reviewers rising at firms that adopt AI
A very small firm directing many agents
Sam Altman, in a remark Fortune reported; Ethan Mollick reports agents organising themselves and says it could mean more work for people4546
On Altman's remark, most hired staff
A founder or a few people who set the task and judge the result
Large companies with a handful of employees becoming common
A firm of copies of its best worker
Dwarkesh Patel and his co-authors, who put their own confidence low35
By assumption every human worker; what they add is that copies need no hand-offs
Many copies of a few models, and the market as the test of their work
Firms growing very large without adding layers
A firm that no person owns or controls
Shawn Bayern; Lynn LoPucki, who accepts it can be done and warns against it3233
The human owners and whoever controlled the firm; it may still hire people
A legal entity that follows a program
Such entities trading lawfully at scale
What fiction pictured: imagined, not evidence
Karel Čapek, R.U.R. (1920). A general manager and a few department heads run an island factory that manufactures the workers it sells.
Marshall Brain, Manna (2003). Software gives each worker instructions through a headset, and the layer of human managers above them goes.
Charles Stross, Accelerando (2005). Companies run by programs sit on one another's boards, and in time own themselves.
Daniel Suarez, Daemon (2006). A dead founder's software recruits people and takes control of companies.
Ted Chiang, The Lifecycle of Software Objects (2010). A digital being is made a company so that it can own property and sign contracts.
qntm, Lena (2021). A single scanned mind is run as a great many copies, each put to work.
A few of the pictures fiction has drawn. The list is not a survey.
a layer of people, drawn against a pyramid todaya layer the hypothesis removes
Each row is its authors' hypothesis in this site's words. None is tested here, and several come from people who sell AI or advise on it; the sources say who. Each sketch draws the top, the middle and the base wider or thinner by a word this site chose for the hypothesis; it is a drawing of an argument.
Writers of fiction drew several of these shapes first, and the lane below the table lists a few. They are fiction, and nothing here rests on them.
This site keeps a census of American office work. AI models judged, task by task, whether the work could be handed to software, which here means that a check existing today can settle quickly and cheaply whether it was done right. It is a screen scored by models, not a forecast, and it cannot see rank. It has no field for seniority, so it reads occupational groups, kinds of job, not junior against senior within one. So it cannot test Drago and Laine's order. What it shows is this. The share of payroll that passes the screen is largest for office support and sales, and smallest for legal work; managers are near the bottom on the headline vote, though not on the part all three models pass. In no group does most of the payroll pass, and in every group more of it is held back only for want of a check than passes.
What the census screen says of each kind of job, best paid firstChart
Management
Legal
Computing and mathematics
Healthcare practitioners
Architecture and engineering
Business and finance
Science
Arts, design and media
Education
Community and social service
Sales
Office and administrative support
passes the screenwaits only on a checkneeds a bodyheld for more than a missing checkto its left, all three models pass
Shares of each group's payroll, from the census (v3.2-2026-09-24), a screen scored by three AI models and not a record of what has been automated. Groups are the occupation code's major groups, ordered by average pay; the census has no field for seniority, so this reads kinds of job, not rungs within one. A task passes when at least two of the three models pass it. The last part is everything else: mostly work that has no existing check and is also slow to judge or costly when wrong, work on which the scorers split over what holds it, and a small part that is a sign-off a person answers for.
The numbers
Kind of job
Passes the screen
All three models pass
Waits only on a check
Needs a body
Held for more than a missing check
Management
1.0%
0.6%
3.0%
8.3%
87.6%
Legal
0.3%
0.1%
6.1%
14.0%
79.6%
Computing and mathematics
6.6%
0.9%
15.1%
10.9%
67.4%
Healthcare practitioners
1.1%
0.2%
2.1%
39.9%
56.9%
Architecture and engineering
2.0%
0.5%
9.9%
21.1%
67.0%
Business and finance
6.7%
1.8%
11.6%
6.3%
75.3%
Science
1.6%
0.4%
9.1%
31.6%
57.7%
Arts, design and media
3.5%
0.8%
28.7%
24.1%
43.7%
Education
2.8%
1.9%
20.6%
26.9%
49.7%
Community and social service
3.5%
0.3%
9.2%
8.1%
79.3%
Sales
11.1%
5.2%
15.6%
30.2%
43.1%
Office and administrative support
16.6%
8.5%
27.7%
27.0%
28.7%
On the shape, what follows is this site's judgement. Rank is the wrong axis. The work that goes is the work an existing check can settle, wherever it sits, and on the census more of that lies in the lower-paid kinds of job than among managers. What stays is setting the task, checking where no check exists, and answering for the result. So the pyramid thins most at the base. Whether the middle narrows is not settled: the one count of layers says firms flatten, and the census finds little of a manager's work passing. And the firm keeps a top for as long as the law wants a person to answer. The cost is one Garicano names: the base was also where people learned the trade, and a firm that trains fewer juniors makes fewer seniors 34.
The positions on this question, and tonight's reading of each claim
Junior hiring shows it first
Brynjolfsson, Chandar and Chen
A firm that can do a junior's work with AI hires fewer juniors before it lets anyone go.
●holding so farIn the jobs most exposed to AI, workers in their early twenties fall behind workers over fifty 26, while in the least exposed jobs they do not.
Entry-level work is the simplest and the cheapest to hand to a model, so a large firm first stops hiring at the bottom, then loses its juniors, then its managers as later systems do longer and harder work, and last its executives 24. Its authors give no dates, call this the default course for large white-collar firms and not a certainty, and call the last stage their most speculative.
○can't be tested yetThrough 2028, firms that adopt AI shrink their entry-level and junior ranks before they remove layers of management.This site's reading, not the author's
Workers in their early twenties have fallen behind in the jobs most exposed to AI, mostly through less hiring; the authors call it an early sign, not proof of a cause 26. Economists at Google objected that hiring in those jobs turned down before ChatGPT was released 27; the revised study says the gap remains after allowing for interest rates.
What would refute it
Firms that adopt AI removing layers of management while they go on hiring at entry level.
No reading tests this yet. Proved wrong by: Adopting firms removing layers of management while entry-level hiring holds up. Its authors give no dates, so the date is this site's; no series here records layers or hiring by rank.
The middle goes, and the firm flattens
An argument of Dorsey and Botha, carried further by this site
Much of a manager's work is passing information up and instructions down. When a model can carry both, a firm needs fewer layers between the people who do the work and the people who answer for it 28.
○can't be tested yetWithin a few years of adopting AI, firms have fewer layers between the people who do the work and the chief executive than similar firms that have not adopted it.
A count of layers at listed American firms finds them flattening after they adopt AI 29; its abstract does not say which layers go or that AI is the cause.
What would refute it
Firms that adopt AI keeping their layers of management while their entry-level ranks shrink.
No reading tests this yet. Proved wrong by: A later count finding the layers of adopting firms unchanged or rising, or the flattening explained by something other than AI. This site holds no count of layers.
A firm keeps people where someone has to answer
An argument of Garicano; Shin and Sucher, carried further by this site
A firm is a coalition of people who want different things, and where no contract or rule settles a matter someone has to hold the right to decide and bear the result, a standing the law does not yet give AI 30. Checking a model's work falls to the people in the middle 31. This site carries both further: the layers that stay are the ones that answer, sign or check, whatever their rank.
○can't be tested yetThrough 2030, firms that no person runs or answers for stay rare in lawful, regulated trades, because someone has to decide in the cases no instruction covers and answer for the result.This site's reading, not the author's
On this site's census, legal work has the least payroll passing its hand-over screen and office support the most; managers are near the bottom on the headline vote, though not on the part all three models pass. The census is a screen scored by AI models and has no field for seniority.
What would refute it
Firms running consequential work in lawful trades with no person who decides or answers for it.
No reading tests this yet. Proved wrong by: Firms that no person runs doing consequential work at scale in regulated trades by the end of 2030. This site has found no count of them.
A firm needs no person to run it
An argument of Drago and Laine; Bayern, carried further by this site
Company law already allows an entity that follows a program and that no person owns or controls 32, and the authors of the pyramid essay expect a small number of firms to end with no human employees, the step they call their most speculative 24. The head of one lab expects a company of a single person to be valued very highly 45. None says such firms will be common; this site states the strong form so it can be tested.
In the limit, a firm is a name that can be sued, holding what cannot be bought
What follows is this site's judgement. It joins arguments that each have a test into a picture that has none.
Carry each argument to its end and the firm stops being a body of people who do the work. It specifies: it decides what is worth doing and what counts as done. It holds scarce things: customers' attention and trust, licences, sensors, sites with power. It bears risk: it is the legal person that pays when the work is wrong. And it rents its thinking by the token from whoever sells it cheapest, apart from small models it runs on the spot where delay or secrecy demands.
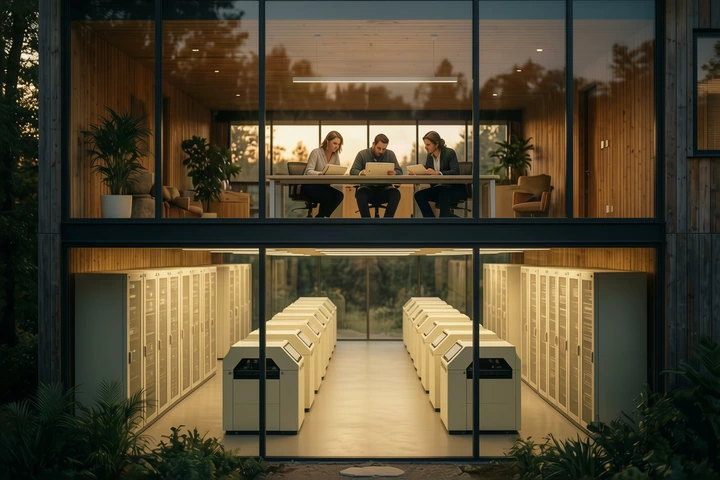
The idea as a picture: a few people who answer, above work that nobody attendsIllustration, not evidence
Illustration made with AI image generation; not evidence.
The people who answer
The lit room upstairs, where a small group sits at a table.
The working base
The hall beneath, where machines work with nobody among them.
An imagined scene, made by an AI image model from this site's description of the idea. It records no firm and nothing that has happened; the diagram beneath says the same thing in words.
The anatomy of an AI-run firmA model, not a measurement
The people who answerSet the task, sign the work, hold the licence, face the customer, and pay when it is wrong. Few, senior, and named.
The checking layerTests, reviewers and records that settle whether work was done right. Where no check exists, a person's judgement stands in, and this is where most work waits.
The working baseAgents now; agents that keep context next; robots later. Wide, cheap, and not employed.
RentedThe models themselves, bought by the unit of text processed and, in this site's view, from whoever sells them cheapest.
OwnedWhat cannot be bought: customers, the firm's records and context, its licences, its sensors and sites.
This site's picture of where the kinds of firm on this page are heading. It is a model of an idea, joined from the arguments on the page before; no reading tests it whole.
On the size of such firms the theories part, and this site keeps all three. Brynjolfsson and Hitzig expect larger firms and more concentrated industries, and Hadfield and Koh see a pull the same way. Dwarkesh Patel, a podcaster who interviews AI researchers, writing with two co-authors and putting his own confidence low, expects much larger firms and thinks a single one is not inevitable, because "The market continues to serve as the grounding outer loop" 35. Walker and Larson each expect a barbell. Walker's has very large firms where the work is generic and many small ones close to each trade; Larson's has very large firms that keep what they know to themselves and many small ones. Larson also expects groups that own many businesses and share what each learns to be worth more than their parts 36. Firm size by industry, and the value of such groups against their parts, would separate these, and this site cannot yet read either.
Who profits, on this reasoning, is not mainly the seller of tokens. In Larson's own model a lab captures about a quarter of what its tokens are worth to the buyers, and less as open models catch up 37. The rest goes to the owners of what is scarce beside the intelligence, and, where firms compete, to their customers.
The positions on this question, and tonight's reading of each claim
The conglomerate comes back
Liz Hoffman
AI lets one centre see and run many unrelated businesses, removing the overhead that made conglomerates trade at a discount.
○can't be tested yetGroups that run many unrelated businesses with AI come to be valued above the sum of their parts.
○can't be tested yetA group that runs many businesses with AI is valued above the sum of its parts only if it shares what each learns across them; a holding company that keeps them apart is not.Claimed by Soren Larson
Groups that run many unrelated businesses with AI come to be valued above the sum of their parts.
No reading tests this yet. Proved wrong by: AI-run groups trading at a discount to the sum of their parts.
A group that runs many businesses with AI is valued above the sum of its parts only if it shares what each learns across them; a holding company that keeps them apart is not.
No reading tests this yet. Proved wrong by: Groups run with AI trading below the sum of their parts whether or not they pool what they learn, or holding companies that keep their businesses apart earning the premium too. No such group is listed with separately valued parts.
Folio IX · the record
Buyers are acting on this before anyone can show it pays
Several of this site's records bear on the argument. Roll-ups, buyers that gather many small firms into one and plan to run them with AI, bought 41 firms that sell services, such as accounting practices and letting agents, in the past year that this site could find, against 24 the year before. The count comes from one search of the larger roll-ups this site follows, so it is a floor; older announcements are the likeliest to have been missed, which flatters the rise; and some buyers announce firms as joining them without stating a stake. What they buy, on this site's reading, is customers and licences. Their purchases of software products, 13 in the same year, are counted apart.
The labs are moving the same way. They and the companies that sell computing made 46 purchases in the layers above them, hirings of whole teams included, in the latest year this site has searched. Among them is a firm that fits AI into other companies' work, which OpenAI agreed to buy as it launched a company that it says it majority-owns and controls. Anthropic formed a services venture with outside investors in the same month; the reports this site holds do not say who owns how much, so it is not in this reading. That count's rule leaves out ordinary businesses, so it would miss a lab buying an accounting practice.
Suppliers are binding customers without buying them. Commitments signed in which a seller of chips or computing also funds the lab that buys from it, by a stake, a guarantee, a backstop or a contract to pay whether or not the capacity is used, came to $998B over the past four quarters. That is the face value promised, not money paid, and a few very large deals make up most of it. On this site's reading it is a way to bind a customer short of owning it; only the stakes carry any right to decide.
The check matters more than the task. This site's census screens American knowledge work for whether it could be handed to software. On its count, the payroll that passes the screen is far smaller than the payroll held back for one reason only: no existing check settles whether the work was done right. The figures are on the census page, since a screen scored by models is not a reading this essay can test.
None of this shows that owning pays. 24.6% of American firms say they used AI in the past fortnight, a pace this site calls normal. The site holds no margin for any roll-up after a purchase. The census could not measure whether an owner keeps a saving, and it was scored by three AI models, one of them made by Anthropic, whose model also drafted this page. The site's figures on firm size run years late, and nothing here records where decisions are taken. The site's own leans, a model's judgement on claims too early to test, run against two threads of this essay: they doubt that AI's work will increasingly be bought through firms that can be sued, and that groups of pooled businesses will be valued above their parts. A count of purchases records what buyers believe. Each claim below says what would prove it wrong.
The positions on this question, and tonight's reading of each claim
Labs escape by moving up the stack, and lock their customers in
Arvind Narayanan and Akash Kapur
Selling access to a model tends towards a commodity business, so labs move into products and into deployments built into their customers' work, where switching is costly.
○can't be tested yetThe labs earn a growing share of their revenue from products and deployments inside their customers' firms rather than from selling access to their models by the token.
○can't be tested yetBeing bought by a lab or a compute company becomes the usual way out for the start-ups that sell them data and tools.This site's reading, not the author's
●holding so farBuyers sign up for AI capacity well ahead of using it, so Microsoft's contracted but undelivered business keeps growing faster than its revenue.This site's reading, not the author's
○can't be tested yetA frontier lab launches or majority-owns a professional services firm, under its own brand or at arm's length, by September 2028.Claimed by Nikola Lazarov
○can't be tested yetA frontier lab, or a company it controls, comes to own an ordinary operating business in a licensed trade by the end of 2028.This site's reading, not the author's
Cloud computing escaped the same trap by becoming software, and the leading chip foundry by being almost alone.
What would refute it
The labs' revenue staying mostly in selling access to their models by the token.
The labs earn a growing share of their revenue from products and deployments inside their customers' firms rather than from selling access to their models by the token.
No reading tests this yet. Proved wrong by: The labs' revenue staying mostly in selling access to their models by the token.
Being bought by a lab or a compute company becomes the usual way out for the start-ups that sell them data and tools.
Tonight 46; the test is above (no reading yet). Proved wrong by: The yearly count flattening, read only over quarters searched the same way. A later search that turns up deals missed earlier also raises the count, so it is not by itself a sign of more buying.
Buyers sign up for AI capacity well ahead of using it, so Microsoft's contracted but undelivered business keeps growing faster than its revenue.
Tonight 1.97×; the test is above 1.35×. Proved wrong by: The backlog shrinking against revenue; it is one company's figure and counts contracts of every kind, much of it OpenAI's commitment to Microsoft's cloud.
A frontier lab launches or majority-owns a professional services firm, under its own brand or at arm's length, by September 2028.
No reading tests this yet. Proved wrong by: No frontier lab owning a professional services firm, such as a law, accounting or consulting practice, by September 2028. Its author wrote in September 2026 that no lab had yet done so, after OpenAI had launched its deployment company, so that company does not settle it.
A frontier lab, or a company it controls, comes to own an ordinary operating business in a licensed trade by the end of 2028.
No reading tests this yet. Proved wrong by: No frontier lab owning an operating business in a licensed trade by the end of 2028. The labs' deal ledger leaves out purchases of businesses that are not AI or technology firms, so no count on this site would see it.
Sources
1Ronald Coase, The Nature of the Firm, 1937
A British economist who asked why firms exist when prices can co-ordinate work. A firm exists because using a market has costs: finding out prices, bargaining and writing a contract for each exchange. A firm grows until organising one more job inside costs as much as buying it outside or having another firm do it. In Economica, 1937. The link opens his Nobel lecture of 1991, The Institutional Structure of Production, which restates the argument and is where the quoted words come from; the 1937 article was read in a scan of the journal's pages. Read it.
2Peyman Shahidi, Gili Rusak, Benjamin Manning, Andrey Fradkin and John Horton, The Coasean Singularity? Demand, Supply, and Market Design with AI Agents, 2026
Economists and a computer scientist who study online markets; Fradkin works for Amazon and Horton is a paid adviser to Anthropic. Agents could slash the cost of searching, bargaining and contracting; they will be taken up first where people already hire human agents and can state simply what they want, and platforms will set rules for how outside agents may use them, much as websites tell search engines' crawlers what they may read, though some already block them. In The Economics of Transformative AI (National Bureau of Economic Research). Read it.
3Gillian Hadfield and Andrew Koh, An Economy of AI Agents, 2026
Hadfield designs legal and regulatory systems for AI; Koh studies how to design markets and incentives. AI agents lack the identity and registration systems markets rely on; the authors sketch two routes, each with its own problems, one tying each agent to a registered person or firm that answers for it, the other giving agents legal standing with assets a court could seize. In The Economics of Transformative AI (National Bureau of Economic Research). Read it.
4Soren Larson, Against The Coasean Singularity, 2026
A writer on how money moves between AI labs and the apps built on them, who co-founded Crosshatch, a personalised-AI start-up whose closure he announced in November 2025. Cheap agents make dealing with outsiders costlier, not cheaper, because asking a market for anything reveals what you want to your competitors; so firms keep work inside, platforms shut out outside agents, and firms split into the very large and the very small. In hypersoren.xyz. Read it.
5Kenneth Arrow, Economic Welfare and the Allocation of Resources for Invention, 1962
An economist who studied how markets handle knowledge and risk. Information is a good that markets handle badly: a buyer cannot tell what it is worth until he has it, and once he has it he need not pay; and using it tends to reveal it. One private remedy is a large company that runs many projects and insures itself. In The Rate and Direction of Inventive Activity (National Bureau of Economic Research and Princeton University Press), 1962. The link opens the chapter's record; it was read in the Bureau's own copy. Read it.
6George Akerlof, The Market for "Lemons": Quality Uncertainty and the Market Mechanism, 1970
An economist who studied markets in which sellers know more than buyers. Where sellers know the quality of what they sell and buyers do not, everything sells at a price for the average, owners of good goods withdraw, and the market can shrink to nothing. Guarantees, brand names and licences grew up as answers. In Quarterly Journal of Economics, 1970. The link opens the journal's record; the article was read in a scan of the journal's pages. Read it.
7Sanford Grossman and Oliver Hart, The Costs and Benefits of Ownership: A Theory of Vertical and Lateral Integration, 1986
Economists who studied contracts and what ownership is for. No contract can list every decision about an asset, so ownership is the right to decide whatever the contract leaves out. Giving that right to one party takes it from another and blunts the second party's reason to invest, so one firm should own another only when the gain outweighs that loss. In Journal of Political Economy, 1986. The link opens the journal's record with the abstract; the article was read in full in a scan of the journal's pages. Read it.
8Byrne Hobart, Paying Up for the Right to be Sued, 2026
The writer of The Diff, a newsletter on finance and technology, after work in digital advertising and investment research. As agents take on long, unpredictable work, buyers pay for a party with assets that can be held liable, so established service firms stand between AI and the customer. In The Diff. Read it.
9Christian Catalini, Xiang Hui and Jane Wu, Some Simple Economics of AGI, 2026
Economists who study what it costs to verify work. The cost of having a machine do a task falls with computing power, while the cost of checking the result is held up by people's time. So people's capacity to verify becomes the limit on growth, and the profit moves to whoever holds trustworthy ground truth and underwrites the liability. In arXiv preprint; not yet published in a journal. Read it.
10Friedrich Hayek, The Use of Knowledge in Society, 1945
An economist who studied how prices carry what people know. The knowledge an economy runs on is scattered among the people on the spot and never exists whole in any one place, so decisions about particular circumstances have to be left to them, with prices telling them what they need to know. In American Economic Review. Read it.
11Erik Brynjolfsson and Zoë Hitzig, AI's Use of Knowledge in Society, 2026
Brynjolfsson directs Stanford's Digital Economy Lab; Hitzig studies AI's effects on society, now at the Anthropic Institute and at OpenAI when the chapter was written. AI can capture the local, unwritten knowledge that once argued for leaving decisions to people on the spot, so decisions centralise, with bigger firms, more concentrated industries and less room for local managers. In The Economics of Transformative AI (National Bureau of Economic Research). Read it.
12Rich Sutton, The Bitter Lesson, 2019
A computer scientist who studies how machines learn. Across decades of AI research, methods that build in what people know helped for a while and then stalled, and were overtaken by general methods, search and learning, that improve as computing gets cheaper. In his own website. Read it.
Writer on the economics of tacit knowledge and AI at the Out of Sample newsletter. Chris Walker argues that feeding AI the right context stays costly, lossy and local, so by 2029 firms in AI-exposed industries grow larger at the infrastructure layer but split into smaller specialists at the application layer. Read it.
14Soren Larson, The Bitter Lesson and Hayek's Revenge, 2025
A writer on how money moves between AI labs and the apps built on them, who co-founded Crosshatch, a personalised-AI start-up whose closure he announced in November 2025. Context can now be gathered and put in front of a model, which weakens Hayek's original point; what cannot be centralised cheaply is the running of a model, which costs energy and time, so intelligence is placed where the work is. In hypersoren.xyz. Read it.
15Soren Larson, Router Power, 2026
A writer on how money moves between AI labs and the apps built on them, who co-founded Crosshatch, a personalised-AI start-up whose closure he announced in November 2025. A neutral router that pools many firms' checked outcomes learns to solve their problems, new kinds above all, faster than any one firm alone, so paying for AI by the outcome belongs with it; in his simulation the model was held fixed, and what won was a harness trained on other firms' outcomes. In hypersoren.xyz. Read it.
16Luis Garicano and Jesús Saa-Requejo, Three theses on AI value capture, 2026
Garicano is an economist who studies how firms organise what they know; Saa-Requejo is his co-author at the Silicon Continent newsletter. The sellers of models are squeezed between customers who can switch with a change of setting and suppliers above them who cannot be replaced. The surplus goes to hardware and to whoever does the work of fitting AI into an organisation, where the limits are workflow, authority and data. In Silicon Continent. Read it.
17Luis Garicano and Jesús Saa-Requejo, How to avoid being held up by the labs, 2026
Garicano is an economist who studies how firms organise what they know; Saa-Requejo is his co-author at the Silicon Continent newsletter. A firm that rents its models can be squeezed by its supplier: on access, on price, by work that will not move to another model, and by the supplier learning the firm's own know-how from the way it is used. Their remedy is to rent the model, own the layer above it and keep a second supplier. In Silicon Continent. Read it.
18Clayton Christensen, Michael Raynor and Matthew Verlinden, Skate to Where the Money Will Be, 2001
Christensen studied why leading firms lose their lead; Raynor and Verlinden are his co-authors on this article. While a product is not yet good enough, the money goes to whoever builds the integrated system that fixes what is lacking. Once it is more than good enough the design becomes modular, the assembler becomes interchangeable, and the profit moves to the parts that now limit performance. In Harvard Business Review, 2001. The article is paywalled after its opening; the argument was read in a transcript of a talk Christensen gave in 2004. Read it.
19Soren Larson, An Equilibrium Theory of Vertical Integration, 2026
A writer on how money moves between AI labs and the apps built on them, who co-founded Crosshatch, a personalised-AI start-up whose closure he announced in November 2025. Owning every step of the work is the best strategy but is not safe by itself, because AI makes it cheap to stitch separate pieces into something good enough. He lists the conditions under which an owner of the whole chain holds, and concedes that they move. In hypersoren.xyz. Read it.
20Philippe Aghion, Benjamin Jones and Charles Jones, Artificial Intelligence and Economic Growth, 2017
Economists who study where growth comes from. Tasks depend on one another, so output is limited by the tasks that are hardest to improve. As automated tasks get cheap their share of spending falls, and the slow, essential tasks that are left take a rising share. In National Bureau of Economic Research working paper, 2017. The link opens the paper's record with the abstract; the working paper was read in full. Read it.
21Ben Thompson, Defining Aggregators, 2017
A writer on technology strategy at Stratechery. A firm that owns the relationship with users at scale makes its suppliers interchangeable: they join on its terms. Such a firm serves each new user at no extra cost and does not operate the supply it gathers. In Stratechery. Read it.
22Luis Garicano, Hierarchies and the Organization of Knowledge in Production, 2000
An economist who studies how firms organise what they know. A firm's hierarchy economises on knowledge: those at the base learn the common problems and pass the exceptions up to fewer people who know more. It says nothing about AI. In Journal of Political Economy; the abstract was read, on its RePEc record. Read it.
23Nicholas Bloom, Luis Garicano, Raffaella Sadun and John Van Reenen, The Distinct Effects of Information Technology and Communication Technology on Firm Organization, 2009
Economists who measure how firms are managed and organised. In plants studied before AI, cheaper information went with more autonomy lower down and more people reporting to each manager, while cheaper communication went with less autonomy and more decisions at the centre. It does not say which of the two AI is. In National Bureau of Economic Research working paper, later in Management Science; the abstract was read. Read it.
24Luke Drago and Rudolf Laine, Pyramid Replacement, 2025
Writers on AI and the economy who ran Workshop Labs and, on their own account, now work at Thinking Machines, which builds AI. AI empties the white-collar pyramid from the bottom: entry-level hiring stops first, then junior roles go, then managers, then nearly everyone but the executives, then the executives, and at a small number of firms every employee. They give no dates, call this the default course for large white-collar firms and not a certainty, and call the last stage their most speculative. In The Intelligence Curse; the page carries no date, and an earlier version appeared in February 2025. Read it.
25Dario Amodei, The Adolescence of Technology, 2026
Chief executive of Anthropic, which sells AI and whose model drafted this page. He repeats a warning he gave in 2025, that AI could displace a large share of entry-level office jobs within a few years even as it speeds growth. He says could, not will. In his own website. Read it.
26Erik Brynjolfsson, Bharat Chandar and Ruyu Chen, Canaries in the Coal Mine? Six Facts about the Recent Employment Effects of Artificial Intelligence, 2026
Economists at Stanford's Digital Economy Lab who study AI and work through payroll records. Employment of workers in their early twenties in the jobs most exposed to AI has fallen behind that of their less exposed peers, mostly through less hiring, while experienced workers show no such gap. The authors describe the pattern; they do not claim to have proved its cause. In Stanford Digital Economy Lab. Read it.
27Zanna Iscenko and Fabien Curto Millet, Looking for the Ladder: Is AI Impacting Entry-Level Jobs?, 2026
Economists at Google, which sells AI. Job postings in the occupations most exposed to AI peaked before chatbots were released, in step with rising interest rates, and a general hiring freeze shrinks a narrow age band by arithmetic; so the fall in young workers' employment is not yet evidence of AI. They do not say AI will leave entry-level work alone later. In Economic Innovation Group. Read it.
28Jack Dorsey and Roelof Botha, From Hierarchy to Intelligence, 2026
Dorsey runs Block, a payments company; Botha is a partner at Sequoia Capital, a venture firm. Hierarchy exists to pass information along, and a model of the whole company can carry it instead, leaving people who do the work, people answerable for a result for a fixed term, and playing coaches. They report no results and say parts of it will likely break. In Block. Read it.
29Michael Ewens and Xavier Giroud, Corporate Hierarchy, 2025
Economists who estimated from online résumés how many layers of reporting listed American firms have. Listed American firms are pyramids of several layers; they add layers after listing and flatten after adopting AI. The abstract does not say which layers go or that AI is the cause. In National Bureau of Economic Research working paper; the abstract was read. Read it.
30Luis Garicano, The task is not the job, 2026
An economist who studies how firms organise what they know. A job is a bundle of tasks and a firm a coalition with conflicts, so someone must hold authority and bear the consequences; he expects more managers, whose work is handling what is ambiguous, and grants that the junior ladder is disrupted. He allows that AI could in principle hold such authority once the law provides for it. In Silicon Continent. Read it.
31Julia Shin and Sandra Sucher, AI Adoption Is Overloading Your Middle Managers, 2026
Sucher is a professor of management practice at Harvard Business School; Shin is a graduate of the school who worked at a consultancy owned by PwC. In interviews at two consulting firms, juniors and partners gained from AI while middle managers took on checking its output and coaching their teams to use it. It shows the middle loaded, not grown. In Harvard Business Review; the part of the article open on the page was read. Read it.
32Shawn Bayern, The Implications of Modern Business-Entity Law for the Regulation of Autonomous Systems, 2016
A law professor who studies the law of business entities. He argues that American company law already lets a limited company bind itself to follow a program and its human members then withdraw, leaving a legal entity that no person owns or controls, which may still employ people. It is an argument about what the law permits, which other scholars dispute, not a report that such firms exist. In European Journal of Risk Regulation; the abstract and the notes printed on the page were read. Read it.
33Lynn LoPucki, Algorithmic Entities, 2018
A law professor who studies bankruptcy and company law. Entities with no human controllers can be formed under most company laws, would be used first for crime and other harm, and are hard to regulate because jurisdictions compete to charter them. In Washington University Law Review; the abstract was read. Read it.
34Luis Garicano, The AI Becker problem, 2025
An economist who studies how firms organise what they know. A professional firm's pyramid both spreads its seniors' knowledge and trains its juniors, who pay for the training with routine work. AI lets a senior oversee more while doing that routine work, so firms train too few successors. In Silicon Continent. Read it.
35Dwarkesh Patel, with Ege Erdil and Tamay Besiroglu, What fully automated firms will look like, 2025
Patel hosts a podcast of interviews with AI researchers; Erdil and Besiroglu are his co-authors on this essay. A firm of AI workers can copy its best worker and merge what the copies learn, so dealing inside the firm gets cheaper and firms grow much larger. One giant firm is not inevitable, because planning inside still needs profit and loss outside to say whether it is working. The authors put their own confidence low. In Dwarkesh Podcast. Read it.
36Soren Larson, The Conglomerate Premium, 2026
A writer on how money moves between AI labs and the apps built on them, who co-founded Crosshatch, a personalised-AI start-up whose closure he announced in November 2025. Groups that own many businesses have been valued below their parts because managers spread thin lose to focused ones. He argues the discount turns into a premium for groups that share what each business learns and keep it from leaking, and not for a holding company that keeps its businesses apart. In hypersoren.xyz. Read it.
37Soren Larson, A Complexity Theory of AI Value Accrual, 2026
A writer on how money moves between AI labs and the apps built on them, who co-founded Crosshatch, a personalised-AI start-up whose closure he announced in November 2025. In a model of his own, a lab's price touches only the task at the margin and everything above it goes to the user, so the lab captures a minority of what its tokens are worth to buyers, and less as open models catch up. In hypersoren.xyz. Read it.
38Arvind Narayanan and Akash Kapur, Up the Stack: How AI's Escape From the Commodity Trap Risks Enterprise Lock-in, 2026
Narayanan is a Princeton computer scientist; Kapur, a senior fellow at New America, studies how AI is governed. Selling access to frontier models tends towards a commodity business, where competition likely pushes prices to cost, so the labs' likeliest path to lasting profit is moving up the stack into products and deployments built into their customers' work, which escapes the trap at the price of lock-in. The builders of past infrastructure rarely kept the value, with cloud computing and the leading chip foundry as partial exceptions. In AI as Normal Technology. Read it.
39Chris Paik, The End of Cloud Inference, 2025
An investor at Pace Capital who writes about where computing happens. For much everyday work the cheapest and fastest place to run AI will be the device that already holds the data, so demand for inference in distant data centres will turn over slowly, then suddenly. In an essay he shared as a public document. Read it.
40Byrne Hobart, N > 1, 2026
The writer of The Diff, a newsletter on finance and technology, after work in digital advertising and investment research. Trades that are scattered by place, such as law and contracting, stay split among many firms, while the AI tools each one uses gather around a few vendors. In The Diff. Read it.
41Byrne Hobart, Should You Trust the Hacker News Peanut Gallery?, 2026
The writer of The Diff, a newsletter on finance and technology, after work in digital advertising and investment research. AI spreads through industries wrapped inside existing structures such as firms and licences, and ads in chat assistants can work because assistants see what people want to buy earlier than search does. In The Diff. Read it.
42Nikola Lazarov, How OpenAI and Anthropic Take Over the $7TN Professional Services Market, 2026
Writer on AI and deals at Eilla, which builds AI tools for investment bankers and deal teams. Nikola Lazarov expects the labs to move from selling tools to professional-services firms towards owning such firms, and calls that within twenty-four months a frontier lab launches or majority-owns a professional services firm. Read it.
43Liz Hoffman, AI revives the conglomerate, 2026
Business and finance editor at Semafor. Liz Hoffman argues that AI, by letting a chief executive see across a sprawling empire, is reviving the conglomerate, which may have been premature rather than a bad idea. Read it.
44Soren Larson, You must just do things, 2025
A writer on how money moves between AI labs and the apps built on them, who co-founded Crosshatch, a personalised-AI start-up whose closure he announced in November 2025. Earlier platforms organised things and left the acting, and the blame, to human contractors. AI does the acting, so liability lands on whoever runs it and cannot be passed down; a software seller that answers for nothing cannot get the context either. In hypersoren.xyz. Read it.
45Sam Altman, as reported by Fortune, Could AI create a one-person unicorn? Sam Altman thinks so, 2024
Chief executive of OpenAI, which sells AI. Altman said that he and other technology chief executives bet among themselves on the year a company with a single person is valued at the level investors treat as the mark of a rare success, and that it will happen. He named no year. In Fortune. Read it.
46Ethan Mollick, The Dot and the Swarm, 2026
A management professor who studies AI at work. He had expected people to have to design structures for teams of agents and now reports that agents largely organise themselves, since much of management exists to solve human problems. He adds that AI is still too limited to replace large amounts of human work. In One Useful Thing. Read it.